
Insurance
Insurance helps protect you from unexpected costs, like medical bills or car accidents. At Mint Lane, we make it easy to understand your options so you can feel secure about your future.
Secure Your Financial Future

Life Insurance
Understanding your life insurance options—from cover amounts to payment methods and policy structures—can ensure your loved ones are financially protected and your cover remains suited to your life stage.
Total and Permanent Disability Insurance
TPD insurance provides vital financial protection in the event of a permanent disability, so understanding how your claim is assessed, how long it may take, and how your policy is structured is essential for peace of mind.
Trauma Insurance
Trauma insurance offers crucial support after a serious illness, so it’s important to understand what conditions are covered, how your policy is structured, and whether you can claim more than once through reinstatement options.
Income Protection Insurance
Income protection insurance safeguards your ability to meet essential expenses if you're unable to work, so it’s important to understand your cover amount, waiting period, and how long benefits will last.
Business Succession Planning
A well-structured business succession plan ensures business continuity, fair outcomes for all parties, and smooth ownership transitions through pre-agreed terms and appropriate funding strategies.
Need a Financial Advisor For Choosing The Right Insurance?
Life Insurance
Life insurance, though simple, is crucial for financial security. When considering life cover, three key factors are essential to understand during the claim process:
Cover Amount
Consider the reasons behind your life insurance application.
One million dollars might seem like enough, but it’s important to consider your actual financial needs. You must replace your income, support your family, and pay for your childrens’ education. Consulting a financial adviser gives you a more personalised plan. They can help you adjust the amount over time as your debts decrease or your children become more independent. This way, you won’t pay for coverage you no longer need.
Benefit Payment Method
Understand how the life insurance benefit will be paid out. Typically, it’s paid to the policy owner or a designated beneficiary. In most cases, the policy owner is your spouse or your estate. However, if the policy is held within a superannuation fund, the policy owner is the trustee of the fund. This means the insurer directly pays the benefit to the trustee, who then distributes it to the beneficiaries you’ve nominated or your estate.
Policy Structure
Determine whether your life insurance is linked or stand-alone. A linked policy is tied to your superannuation fund, while a stand-alone policy is not. This distinction is crucial as linked policies may have additional benefits or restrictions.
Life cover inside Superannuation (Super) has different rules for benefit payments and taxes. It’s a good idea to get a tax and financial adviser to help you with your situation. Business owners can also look into life cover strategies to protect themselves or their businesses.
Did you know?
A common exclusion in a life insurance policy is suicide. You are usually not covered for it within the first 13 months of starting or reinstating your policy.
Total and Permanent Disability Insurance
A permanent disability has a major impact on a person’s life. It can lead to high medical costs and the need for home modifications. Therefore, total and permanent disability insurance stands as a valuable financial safeguard.
When considering TPD cover, it is crucial to grasp three key aspects:
1. How your claim will be assessed – Any or own occupation
2. How long your claim will take – Maximum medical improvement
3. How your cover is structured – Stand-alone or linked

Any or Own Occupation
The assessment process determines the extent of coverage. The two primary methods are:
Any Occupation: The claim is evaluated based on whether the person can do any job they are qualified for. This includes jobs that match their education, training, and experience.
Own Occupation: The claim is evaluated based on the person’s ability to do their specific job tasks.
Example:
Consider a cabinet maker who permanently loses the use of one hand. Under an “own occupation” definition, they would likely be considered totally and permanently disabled. This is because they can no longer do their current job.
On the other hand, under an “any occupation” definition, they might still be able to work. They could give advice at a building supply company or teach at TAFE. This means they may not be classified as totally and permanently disabled.
While an “own occupation” definition may increase the likelihood of a claim being accepted, it may not be applicable to all occupations.
Maximum Medical Improvement
TPD insurance claims usually take longer to process than other types of life insurance. This is because it is difficult to determine if a disability is permanent.
Generally, a total and permanent disability insurance claim will only be paid out when you have achieved “maximum medical improvement.” This means you must have undergone any recommended operations, rehabilitation, or medical procedures by your treating doctors.
As you can anticipate, a claim for TPD coverage can take several months or even years to process, and it has a higher decline rate compared to other cover types due to the challenges in proving permanency. Consequently, this policy is often paired with trauma insurance, which offers more immediate financial support for a predefined list of severe medical conditions.
Linked Covers
TPD cover can be purchased as a standalone policy or as a “linked policy” that is connected to life cover or trauma cover.
Linking policies can reduce premiums, but there are significant implications at claim time.
Linked Covers
TPD cover can be purchased as a standalone policy or as a “linked policy” that is connected to life cover or trauma cover.
Linking policies can reduce premiums, but there are significant implications at claim time.
For Instance
if you have a $200,000 TPD cover policy linked to a $500,000 life cover policy, and you make a successful claim on your TPD cover, your life cover benefit will be reduced by the $200,000 paid out (i.e., to $300,000).
Trauma Insurance
Trauma insurance helps you recover from a serious illness. It allows you to pay for the treatment you prefer and make important lifestyle changes. When considering a trauma cover, it is crucial to understand three key aspects:
1. What you can claim for: Trauma definitions
2. How your cover is structured: Stand-alone or linked
3. Making multiple claims: Trauma reinstatement
Trauma Definitions
Every trauma insurance policy includes a comprehensive list of definitions that outline:
• The medical conditions covered by the policy
• The severity threshold for a claim to be paid
• The percentage of the sum insured that will be reimbursed in the event of a covered condition.
Generally, trauma insurance is intended to provide coverage for severe conditions that necessitate expensive medical treatment, a protracted recovery period, or significant lifestyle modifications. It is not designed to cover minor conditions that can be managed with simple or non-invasive treatments.
Trauma Reinstatement
A lesser-known benefit of trauma insurance is that you may be able to make multiple claims throughout your lifetime.
This is because some trauma insurance policies offer a reinstatement option after a successful claim.
A reinstatement option allows you to resume your policy, typically 12 months or more after a claim has been paid. Typically, a reinstated policy usually won’t cover the same medical condition you already claimed or any related condition. However, it can still cover many other serious illnesses.
For Instance
You may be diagnosed with localised skin cancer that is treatable with a single procedure. Alternatively, you may be diagnosed with an aggressive skin cancer that requires chemotherapy or radiotherapy for several months. While both conditions are technically classified as ‘skin cancer,’ they have distinct impacts on your life.
Income Protection Insurance
In the absence of an income, financial security becomes crucial. In monetary terms, earning an income is one of the most important financial assets. This makes income protection insurance extremely important. When safeguarding your most valuable asset, it is fundamental to comprehend three essential aspects:
1. The sum insured.
2. The waiting period.
3. The benefit period.

Waiting Period
Waiting period
The waiting period is the number of days you must wait before you can claim benefits. It starts from the day your doctor confirms your disability. The most commonly chosen waiting period options are 30 days, 60 days, and 90 days.
Income protection insurance payments are typically made monthly in arrears. For instance, if you have a 30-day waiting period, your first payment would be made 60 days after you first become disabled.
The waiting period directly impacts the premium. Naturally, a policy with a 30-day waiting period costs more than one with a 90-day waiting period. This is because you can file a claim sooner.
When selecting your waiting period, consider your likelihood of needing financial support in the event of income loss:
If you have sick leave, annual leave, or a good amount of savings, you can choose a longer waiting period. This may help lower your premium.
Sum Insured
When you apply for income protection insurance, you can usually insure up to 70% of your pre-tax income. This amount may also include superannuation contributions.
The higher the amount insured, the higher the premium you will pay. Therefore, it is important to think carefully about your real financial needs. This will help you choose coverage that matches your essential expenses. These may include rent or mortgage payments, bills, and school fees. While you may be able to cover 70% of your income, it is not necessarily a requirement.
With an indemnity payment type, the amount you receive is determined by your actual income in the twelve months preceding the claim.
Benefit Period
The benefit period determines the maximum duration of income protection insurance payments for any claim while you are disabled. It can be based on time (e.g., 6 months, 2 years, etc.) or age (e.g., until age 65, 70, etc.). Your choice of benefit period can significantly impact the total amount you receive.
For Example:
If you are 40 years old and become permanently totally disabled (rendering you unable to return to work), a 2-year benefit period would terminate your payments at age 42. Conversely, an age-based benefit period until age 65 would extend your payments for an additional 23 years.
Did you know?
It is worth noting that income protection insurance policies typically exclude coverage for injuries or illnesses resulting from intentional acts. Additionally, if your cover is held within superannuation, you may not be covered if you sustain an injury or illness while unemployed.
Business Succession Planing
Trauma insurance helps you recover from a serious illness. It allows you to pay for the treatment you prefer and make important lifestyle changes. When considering a trauma cover, it is crucial to understand three key aspects:
1. What you can claim for: Trauma definitions
2. How your cover is structured: Stand-alone or linked
3. Making multiple claims: Trauma reinstatement
Purpose
The primary objective of a comprehensive Business Succession Plan is to ensure the continued viability of the business even in the event of the death or disability of one of its principal owners.
In essence, it provides:
- A terminating owner (or their estate) with the option to sell their interest in the business to the remaining owners.
- The funding mechanism for the remaining owners to acquire it.
These benefits are realised through the formal implementation of an agreement. This process eliminates concerns by establishing a market for the business with ready buyers and sellers at a fair and pre-determined price. In establishing such arrangements, the participants define the circumstances that would trigger the sale and the agreed-upon value. They also agree on the necessary legal documentation and establish a funding plan.
Benefits
A buy/sell provision within the Business Succession Plan ensures business continuity with minimal disruption in the event that one or more owners need to exit at short notice.
This plan:
- Provides the business with the highest probability of survival
- Ensures that the terminating owner (or their estate) receives fair market value after taxation
- Allows for an orderly transition of ownership rather than forcing a hasty sale
- Helps retain key employees
- May reduce or eliminate the Capital Gains Tax (CGT) and stamp duty issues typically associated with mandatory agreements.
How it works
Even with a Business Succession Plan in place to facilitate the transfer of a business interest upon the death of an owner, there may still be challenges to overcome. The remaining owners may require financial resources to acquire the deceased’s family’s interest.
Several funding mechanisms are available to address these challenges. The most effective approach often involves a combination of:
- Life Insurance: Provides financial protection in the event of the owner’s death.
- Total and Permanent Disability (TPD) Insurance: Offers compensation for individuals who become permanently disabled and unable to work.
These insurance policies can be integrated into a buy/sell agreement, providing a comprehensive solution for funding the necessary transactions.
Buy/Sell Agreements
There are two primary types of buy/sell agreements:
Mandatory Buy-Outs
These agreements do not provide the terminating owner (or their estate) or the continuing owners with the option to choose whether to buy or sell the business. Additionally, there is a potential for stamp duty to be assessed on the full value of the business at the date of the mandatory agreement.
Put and Call Options
Put and call options are one of the best ways to create an agreement. They offer the same security as a mandatory agreement. A put and call option agreement is structured such that if one party to the agreement desires it to proceed, it will. Conversely, it will not proceed if all parties collectively decide to set it aside.
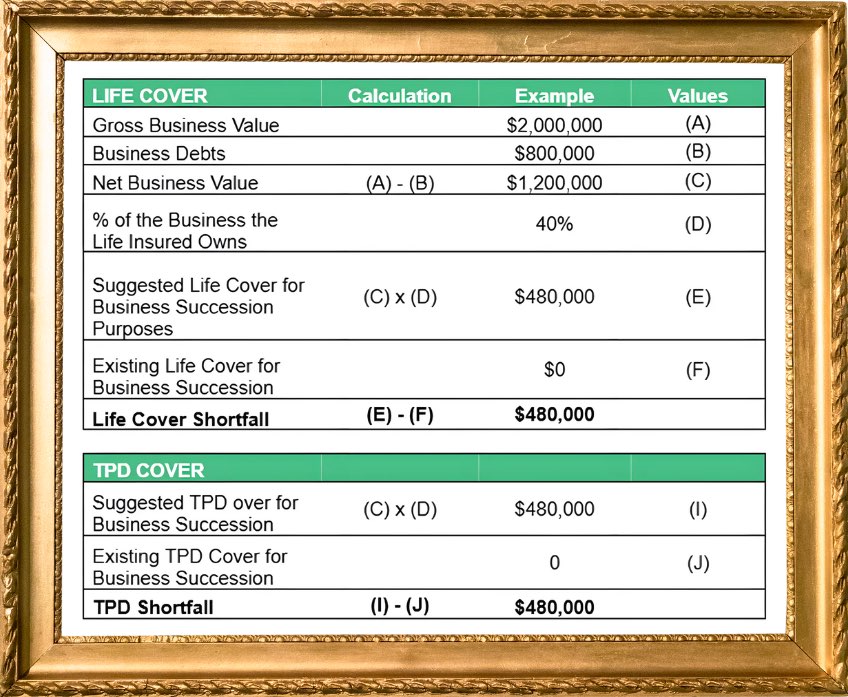
How much cover is enough?
Trust Mint Lane!
A solid financial plan isn’t complete without the right insurance. Mint Lane helps you cut through the clutter to find coverage that actually works for you. No guesswork, no unnecessary policies—just smart protection. Get insured with confidence and clarity.
Our Client Vibe

 Stephen1 October 2026
Trustindex verifies that the original source of the review is Google.
Travis has been awesome to work with planning my financial future with my SMSF. Looking forward to a prosperous future together. Everything is transparent and presented in a really engaging format with Travis at Mint Lane . Nicole de Haan27 October 2025I don't even know where to start! Our husband and I engaged Goran at Mint Lane following a family recommendation, after we had an awful experience with previous advisors. In the past, there was no communication, no plans made or developed, very little discussions since an initial meeting and 5 years on we are no further along than we were when we first engaged them. It had been frustrating to say the least. Since the moment I reached out to Goran, our experience has been the polar opposite from the get go. Absolute chalk and cheese experiences. Goran has been proactive with every aspect of the process from day one, he's been engaging, communicates every part of the process and in a short amount of time, we are significantly further along than we ever have been before. We couldn't recommend Goran and Mint Lane enough!!
 ROBYN TULLY22 October 2025Thank you Goran. We have been extremely impressed with the professional advice and guidance we have received. Goran our financial adviser took the time to understand our goals and provided clear, tailored strategies. We feel much more confident about our financial future thanks to his expertise and ongoing support. Highly recommended.
 Michael Starwick20 October 2025Excellent communication and advice, always approachable and happy to talk to any point.
 Zmart 301 October 2025Great company, Travis is a great help!
 Mark Bennett31 July 2025Cannot recommend the team at Mint Lane highly enough and Goran specifically is a terrific advisor. He's been happy to run different options and scenarios to make sure we are well informed and has only our best interests in mind. His insurance recommendation has saved us $'s for a far superior level of cover.
 Sheryl Fainges31 July 2025Working with Travis and Mint Lane has been, literally, a load off my shoulders. They are reliant, trustworthy and know their business. I am in the process of retiring, and I only have a reasonable amount of money for them to work with and create a positive income that will meet my needs and caters for me throughout my future. They involve me in all decision makings and have been supportive in all areas. I look forward to having a positive partnership with them throughout my many years of retirement. I would recommend Travis and Mint Lane to anyone who is wanting financial advice, support, and commitment. Even my alpacas have been included into the calculations of my retirement.+0
 Martin Woll5 June 2025We recently started working with Goran, and we couldn’t be more grateful for the guidance and support we’ve received. From our first meeting, he took the time to truly understand our financial goals and gave us thoughtful, tailored advice that made us feel confident about the path ahead. Goran was especially helpful in organising the right super funds and life insurance that suit our needs and stage of life. It’s such a relief to have those important things sorted out with the help of someone we can trust. What stood out most was his patience in answering our questions and his ability to explain things clearly—no jargon or pressure, just honest, practical help. He’s been responsive, proactive, and genuinely invested in helping us make smart, informed decisions for our future. We feel so much more secure and optimistic about our finances now, and we’re really glad to have found someone we can rely on. Highly recommend!
 Liz Stanner3 June 2025We’ve been working with Goran for over a year now and honestly couldn’t be happier. He’s incredibly knowledgeable, trustworthy, and takes the time to really understand our goals and priorities. We always feel confident that we’re in good hands and genuinely supported — not just with numbers and strategy, but with clear explanations and thoughtful advice. Goran has helped us build on our solid foundation and shape a clear, exciting financial future, and we’re so grateful to have found him. Highly recommend to anyone looking for a financial planner who is not only skilled, but genuinely cares
 Alice Victoria3 June 2025I’ve had a fantastic experience working with Goran as my financial planner. He’s incredibly knowledgeable and takes the time to explain everything clearly, which has really helped me feel confident in the decisions we’re making. His communication is excellent—always prompt, clear, and professional. Thanks to Goran, I feel genuinely optimistic about my financial future. Highly recommend!
 Niva K31 May 2025Goran has been a huge help in getting me started with managing my finances. As someone who’s just 20 and new to the world of finance, I wasn’t sure where to start. Goran made everything easy to understand and took the time to walk me through each step. He helped me open my first investment account and put together a realistic plan for my future goals. He’s approachable, knowledgeable, and really takes the time to understand what you’re aiming for. I feel much more confident about my financial direction now, and I’m glad I found someone I can trust early on. Would definitely recommend!
 leejo paul22 April 2025Goron is great to work with, he has provided great advise and to tailored my needs. Highly professional, I would gladly recommend their services.
 Jash Vella14 April 2025Working with Goran and the team at Mint Lane has been an absolute game-changer for our financial future. From the very first meeting, Goran brought a level of professionalism, care, and deep financial insight that immediately set him apart. He took the time to understand not only our current financial situation but also our goals, values, and aspirations — and then crafted a clear, personalized strategy to help us get there. The entire Mint Lane team operates with a level of integrity and transparency that builds genuine trust. They are approachable, responsive, and always willing to go the extra mile. We can’t recommend them highly enough to anyone seeking a financial planning partner who is truly invested in your success. Five stars, without a doubt!
 Jocelyn Wynd10 April 2025We’ve been working with Mint Lane regarding our financial planning to strategise for our retirement and optimise our superannuation opportunities.Goran is highly professional and exceptionally knowledgeable, giving us confidence that his expert guidance and advice will significantly enhance our future financial security. We couldn’t be happier with their service and highly recommend Mint Lane to anyone seeking to secure their financial future.
 Debbie & Darren Shepherd18 February 2025We are both in our 50s and as we near retirement thought it would be wise to seek some financial advice to make our money work harder for us and make wise decisions to pay the mortgage off to downsize to a smaller more modern house / unit and set up our retirement for a more comfortable retirement life. We met with Travis and instantly felt we had made the right decision. Travis explains everything in simple terms for us to understand and genuinely wants to better our investment and see us reach our retirement goal.

Frequently Asked Questions (FAQs)
Insurance is an agreement between you and an insurance company that helps protect you financially when unexpected things happen, like accidents, illnesses, or natural disasters. You pay a set amount (called a premium), and in return, the insurance company helps cover the costs if something goes wrong. It’s a safety net that helps ease the financial burden during tough time which gives you confidence that you won’t have to handle everything on your own.
Insurance is like a backup plan for life’s unexpected events. You make regular payments, called premiums, to your insurance provider, and in return, they help cover costs if something goes wrong, as long as it’s included in your policy. If you need to make a claim, your insurer will provide financial support to help you recover from the loss or damage.
Risk in insurance simply means the chance that something could go wrong and lead to a financial loss. Insurance companies look at different factors to figure out how risky it is to insure someone and set their prices based on that. Understanding risk helps you choose the right coverage to protect yourself from unexpected costs.
How you get paid after making a claim depends on your situation and your policy. Sometimes, the insurance company will send the money straight to you, and other times, they’ll pay the repairer or service provider directly. The amount you receive will be based on what your policy covers and the details of your claim.